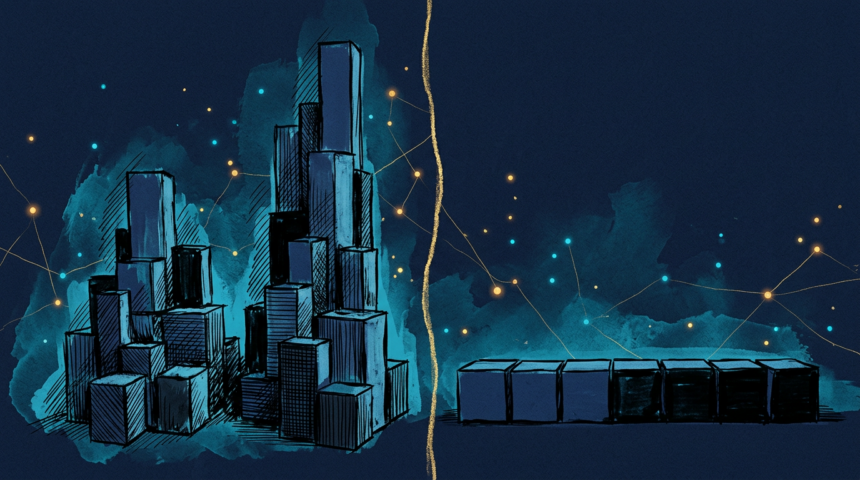
A note from Apollo Global Management’s chief economist has become the week’s most-shared argument about what AI has actually delivered. Torsten Slok split the S&P 500 into two halves and found the gap widening fast.
He calls the lower group the S&P 493, meaning the index minus Alphabet, Amazon, Apple, Meta, Microsoft, Nvidia and Tesla. Across those companies, revenue per worker has barely moved. Profit margins are equally flat. Both measures keep climbing for the seven giants.
Slok’s conclusion is blunt. Despite enormous spending and louder hype, the technology has handed corporate America outside tech nothing measurable on the bottom line. Cheap intelligence, he argues, is not the same as higher growth, and turning one into the other is harder than the vendors suggest.
His reasoning leans on what intelligence does inside a business. Judgment, trust, accountability and unwritten rules decide whether a customer stays. A model that answers questions well does not carry any of that, and it cannot own a mistake.
The timing sharpens the point. Microsoft has guided toward roughly $190B in 2026 AI capital spending, and Meta has floated up to $135B. Those outlays land on the seven companies seeing the returns. Everyone else is paying for tools and waiting.
Other research has landed in the same place this month. Studies of coding assistants and office copilots keep finding modest gains that shrink once review, rework and coordination costs are counted.
For buyers, the practical read is narrow. Pilots still need a measured baseline before renewal, and vendors will be asked to show margin movement rather than seat counts. Slok did not forecast a bust. He simply recorded that the payoff has yet to arrive.